
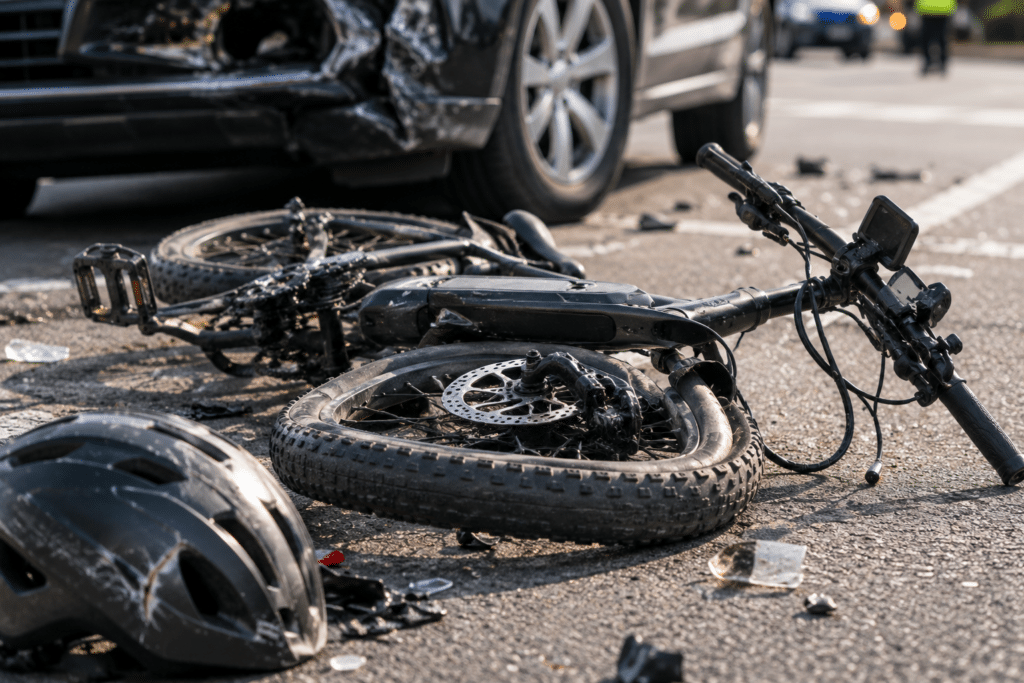
When an E-Bike Crash Causes a Severe Damage, Who Pays?
As electrical bikes grow to be abnormal transportation, private damage claims are exposing an insurance coverage drawback many riders and households don’t take into account till after a collision
Electrical bikes have moved shortly from novelty to abnormal transportation. They’re used for commuting, errands, recreation and supply work in cities, suburbs and smaller communities. The damage image has modified simply as shortly. The tougher query typically arrives after the ambulance leaves: when an e-bike crash causes a traumatic mind damage, a number of fractures or one other life-changing damage, what insurance coverage is definitely accessible to pay the sufferer?
The federal numbers clarify why that query deserves consideration. The U.S. Shopper Product Security Fee’s April 2026 micromobility report estimates 155,200 emergency-department visits related to e-bikes from 2017 by means of 2024. CPSC employees additionally recognized 310 reported e-bike fatalities throughout that interval, though the company cautions that latest fatality counts stay incomplete as a result of reporting can lag.
These figures seize solely a part of the authorized drawback. A automotive crash normally begins with a well-recognized insurance coverage framework. An e-bike collision might not. The machine might belong to an grownup, a youngster, an employer or a supply employee. It could have been bought as a bicycle however modified to journey sooner. The collision might occur on a public highway, a sidewalk, a non-public driveway or inside a residential group. Every reality can change the place an injured particular person appears for compensation.
“Folks see two wheels and pedals and assume the insurance coverage points will appear like a bicycle accident,” says private damage legal professional and authorized analyst Rusty Reynolds, Founding Accomplice of the Reynolds & Reynolds Legislation Agency. “That assumption could be costly. The primary job after a critical damage is to establish each particular person, coverage and entity which will have obligation. You don’t cease the investigation as a result of there isn’t any standard auto coverage connected to the e-bike.”
The insurance coverage query begins with the information
Potential protection can depend upon who owned the machine, who was driving it, the place the crash occurred, whether or not the rider was working and what the related insurance policies truly exclude. Owners or renters legal responsibility protection might warrant evaluation in some instances. An umbrella coverage may matter. A industrial coverage might enter the evaluation when the rider was working. Specialty protection might exist for sure leisure autos. None of these potentialities needs to be assumed, and none applies mechanically.
Reynolds says that is the place injured folks could make a pricey mistake by accepting the primary reply they obtain. “If somebody tells you, ‘There is no such thing as a insurance coverage as a result of it was an e-bike,’ that ought to not essentially finish the inquiry,” he says. “Protection is a contract query. Legal responsibility is a information query. It is advisable to know who owned the machine, who managed it, the way it was getting used, the place the collision occurred and what insurance policies have been in pressure earlier than you can also make a accountable evaluation.”
The excellence issues as a result of the accidents could be extreme. CPSC’s 2024 particular research discovered that 58 % of estimated e-bike accidents occurred on paved roads and 24 % have been related to motor-vehicle accidents. Fifteen % of riders within the research have been touring at 20 mph or sooner when the accident occurred. These aren’t trivial speeds when a rider collides with a pedestrian, one other bike owner or a automobile.
Excessive-powered units complicate the legal responsibility evaluation
The class itself has grow to be much less tidy. Federal consumer-product legislation defines a low-speed electrical bicycle utilizing particular gear and efficiency standards, together with operable pedals, a motor underneath 750 watts and a most motor-powered pace under 20 mph underneath specified check circumstances. Merchandise bought and utilized in the actual world don’t at all times keep neatly inside these boundaries.
Some units could be modified. Others could also be marketed in ways in which make them appear like standard e-bikes despite the fact that their energy or pace locations them in a distinct authorized class underneath state or native legislation. That classification can have an effect on visitors guidelines, permissible driving areas and the insurance coverage evaluation after a collision.
“Velocity adjustments the damage potential, however it could actually additionally change the authorized questions,” Reynolds says. “If a tool has been altered to carry out far past its unique specs, I wish to know who made the modification, who knew about it and whether or not the automobile was legally allowed to function the place the crash occurred. These information can grow to be essential in a critical damage case.”
Dad and mom face a separate set of questions
Youth use provides one other layer. A father or mother might view an e-bike as a sensible approach for a youngster to get to high school or go to buddies. From a private damage standpoint, the related questions embody the kid’s age, the ability and pace of the machine, native working restrictions, the kid’s expertise and whether or not the grownup who provided the machine understood how it might be used.
Claims involving minors can elevate theories resembling negligent entrustment or negligent supervision, relying on the jurisdiction and information. State legislation varies, so there isn’t any single nationwide rule that makes a father or mother mechanically liable at any time when a toddler causes an e-bike collision.
Reynolds advises households to deal with the acquisition extra critically than they could deal with a standard bicycle. “Earlier than you hand a younger rider the controls, discover out precisely what the machine can do,” he says. “Verify the age guidelines the place you reside. Verify the place it could actually legally be ridden. Then name your insurance coverage agent and ask a really particular query: if my youngster injures somebody whereas working this precise e-bike, what protection do I’ve? Get the reply earlier than there’s a declare.”
A crash investigation ought to comply with the proof
For an injured pedestrian or rider, early proof can matter. Pictures of the machine might set up its make, mannequin and modifications. App knowledge, buy data, video, witness data and delivery-platform data might help present how the automobile was getting used. In a hit-and-run, surveillance footage and immediate reporting might grow to be particularly necessary as a result of figuring out the rider can decide whether or not extra sources of restoration could be investigated.
The identical self-discipline applies when a automotive hits an e-bike rider. CPSC discovered motor-vehicle accidents among the many main hazards related to e-bike fatalities. An injured rider mustn’t assume that driving an e-bike diminishes the duties owed by a negligent motorist. Fault nonetheless activates the circumstances of the collision and the legislation of the jurisdiction.
“The label on the automobile ought to by no means change the investigation,” Reynolds says. “Was the motive force dashing? Was the rider the place the legislation allowed? Was there a visibility drawback? Was the machine modified? Was somebody working on the time? These particulars decide legal responsibility. The truth that an e-bike was concerned is the start of the evaluation, not the reply.”
As e-bikes grow to be routine transportation, private damage legislation is being pressured to take care of crashes that don’t at all times match the insurance coverage assumptions constructed round automobiles and conventional bicycles. For victims, that makes the primary protection search extra necessary, not much less. A critical damage can create years of medical prices and misplaced revenue. The accountable query will not be whether or not the e-bike carried an auto insurance coverage card. It’s who could also be legally accountable and what protection, belongings or different sources of restoration truly exist.
~~~
Entrepreneur Management Community member Merilee Kern, MBA is an internationally-regarded model strategist and analyst who studies on cultural shifts and tendencies in addition to noteworthy trade change makers, movers, shakers and innovators throughout all classes, each B2C and B2B. This contains subject consultants and thought leaders, manufacturers, merchandise, companies, locations and occasions. As Founder, Govt Editor and Producer of “The Luxe Listing,” Merilee is a prolific enterprise, way of life, journey, eating and leisure trade voice of authority and tastemaker. She retains her finger on the heart beat of {the marketplace} searching for new and modern must-haves and exemplary experiences in any respect worth factors, from the reasonably priced to the intense. Her work reaches multi-millions worldwide by way of broadcast TV (her personal exhibits and copious others on which she seems) in addition to a myriad of print and on-line publications. Join together with her at www.TheLuxeList.com / Instagram www.Instagram.com/MerileeKern / X http://www.X.com/MerileeKern / Fb www.Fb.com/MerileeKernOfficial / LinkedIN www.LinkedIn.com/in/MerileeKern.
***Some or the entire lodging(s), expertise(s), merchandise(s) and/or service(s) detailed above might have been supplied or organized without charge to accommodate if that is evaluation editorial, however all opinions expressed are solely these of Merilee Kern and haven’t been influenced in any approach.***
Supply